Shareholders push banks as recapitalisation deadline nears
CBN logoWith roughly three months to the end of the expiration of the deadline for recapitalisation in the banking sector, shareholder groups have demanded action from banks that are yet to cross the minimum capital requirement thresholds.

In separate interviews with The PUNCH over the weekend, the leaders in the minority investors community lamented that they would be worst hit if banks fail to meet the new MCRs ahead of schedule.

After the last Monetary Policy Committee meeting of 2025, the governor of the Central Bank of Nigeria, Olayemi Cardoso, disclosed that 16 banks have achieved full compliance with the revised capital requirements, ahead of the deadline.

Cardoso reiterated CBN’s commitment to ensuring an orderly end to the recapitalisation exercise during a presentation at the U.S.-Nigeria Executive Business Roundtable held in Washington, D.C., this week. According to THISDAY, which obtained a copy of the presentation, Cardoso said, “Nigeria is now in the final phase of its most significant banking-sector strengthening effort in over a decade. The recapitalisation programme is designed to safeguard financial stability, expand banks’ capacity to lend, and ensure the financial system is able to underpin Nigeria’s broader economic transformation.

“We’re making good progress. 16 banks have already met or exceeded the new capital thresholds, while 27 have raised capital through public offers, rights issues, private placements, and mergers.”

While hailing the feat achieved thus far and expressing confidence in the ability of the remaining banks to meet the MCR, the minority investors’ community also fears that they would be left holding the short end of the stick if some of the banks don’t meet the threshold.

National Coordinator of the Independent Shareholders Association of Nigeria, Moses Igbrude, said, “The banks’ recapitalisation hurdle so far has been very impressive and encouraging, seeing about 16 banks crossing the hurdle. The most impressive part of it is how investors, especially the Nigerian investors, embraced and keyed in to the various offers that were made to the point of oversubscription. It is a sign that investors, both local and international, have strong confidence and believe in the Nigerian capital market.

“As the deadline comes closer, I have the confidence that the remaining banks are in the various stages of capitalising; after all, there are different banking licences: regional, national and international licences. If you cannot meet the highest category, you go for the lower one.

As for the nationalised banks, the government should recapitalise them through the CBN, which is running them on behalf of the FG. After the recapitalisation process, the FG should privatise them by selling 60 per cent to qualified core investors and the remaining 40 per cent to the Nigerian people to recover the money used to recapitalise them and list the shares on the floor of the NGX.”

To the banks still lagging, Igbrude said, “If there are banks that are not making headway, they should do so now through all available means, both private placement and mergers and acquisitions, or opt for the lowest licence available to avoid revocation of their licences. Let them not say there is still time.  Let them make hay while there’s sunshine.”

The National Coordinator of the Pragmatic Shareholders Association, Bisi Bakare, in her comments, called for speed: “The recapitalisation process is going on well so far, and according to CBN, only 16 banks have concluded their capital raising.  It’s my opinion that as deadlines draw closer, banks should hasten up for merger, strategic realignment or be outrightly acquired by other strong banks rather than waiting for the CBN regulatory hammer, which would not work in their favour nor shareholders’ (investors’).”

The chairman of the Ibadan Zone Shareholders Association, Ayoola Gilbert, called on the CBN to be prepared with clear contingency plans to safeguard the system’s integrity as the recapitalisation deadline gets closer.

“This policy is not just about bigger numbers on the bank’s balance sheet. The CBN has positioned it as a foundational pillar for achieving a $1tn economy by 2030. The core objectives are to create banks strong enough to withstand domestic and global economic shocks while enabling banks to take on larger risks and provide the substantial credit needed to fund critical national projects and support key sectors like MSMEs. If a significant number of banks are still scrambling as of the fourth quarter of 2025, the consequences will ripple through the entire financial ecosystem, directly impacting consumers, shareholder value and systemic trust.

“The successful banks like Access Holdings, Zenith Bank, and Wema Bank, which have raised hundreds of billions, demonstrate that recapitalisation is achievable and can be rewarded by the market. Their strength positions them to lead financing for Nigeria’s growth. As shareholders, we must urge the boards and management of our banks to exhaust every option, be it rights issues, private placements, or strategic mergers, with urgency. Simultaneously, we call on the CBN to communicate a clear, transparent contingency framework well before the deadline. Knowing the rules of a potential orderly consolidation will do more to maintain confidence than a last-minute regulatory scramble.”

Indigenous operators now power Nigeria’s energy future – IPPG

The Independent Petroleum Producers Group has marked its 10th anniversary, celebrating a decade of resilience, collaboration, and transformative impact in Nigeria’s oil and gas industry.
Speaking at the milestone event, the IPPG Chairman and Chief Executive Officer of Aradel Holdings, Mr Adegbite Falade, described the journey as “a decade defined by purpose, partnership, and impact,” according to a statement from IPPG on Sunday.

He said the anniversary was not merely a celebration of longevity, but a reaffirmation of the Group’s shared commitment to strengthening indigenous leadership and advancing Nigeria’s energy sector.

“This anniversary marks a decade in which indigenous operators have demonstrated their capacity to lead, deliver value, and shape the future of Nigeria’s energy sector,” Falade said.

Over the past 10 years, IPPG has evolved into a leading industry voice and a credible partner in sector development.

Through sustained advocacy and collaboration with government and regulators, indigenous operators now account for over 50 per cent of Nigeria’s crude oil and gas production, an achievement widely regarded as evidence of IPPG’s growing influence and effectiveness.

Falade commended the administration of President Bola Tinubu for reforms aimed at repositioning the sector for growth and investment. He also acknowledged the support of the Ministers of State for Petroleum Resources, the Special Adviser to the President on Energy, and the leadership of key institutions, including the Nigerian Upstream Petroleum Regulatory Commission, the Nigerian Midstream and Downstream Petroleum Regulatory Authority, the Nigerian Content Development and Monitoring Board, and the NNPC Limited.

Reflecting on the anniversary theme, “Building on a Decade of Impact,” Falade reaffirmed IPPG’s commitment to supporting government efforts to achieve energy security, particularly in the wake of International Oil Company divestments. He stressed that responsibility now rests squarely on indigenous operators to deliver sustainable production growth.

Representing President Tinubu at the event, the Minister of State for Petroleum Resources (Oil), Senator Heineken Lokpobiri, described IPPG as a critical force in the industry and “one of the best things to have happened to Nigeria’s oil and gas sector.” He also cited the appointment of Mr Ademola Adeyemi-Bero as Nigeria’s OPEC Governor and Chairman of the OPEC Board of Governors for 2025 as global recognition of indigenous capacity.

The celebration featured a high-level fireside chat focused on indigenous leadership and the future of the industry, alongside Leadership Recognition Awards honouring distinguished members and sector leaders.

Looking ahead, IPPG reiterated its resolve to contribute meaningfully to Nigeria’s targets of producing three million barrels of oil per day and 12 billion standard cubic feet of gas by 2030. Over the next five years, the Group said it would prioritise infrastructure expansion, host community engagement in the Niger Delta, capacity building, strong governance, and responsible resource development.

As IPPG enters its second decade, the Group reaffirmed its commitment to act as a catalyst for Nigeria’s economic transformation and industrialisation by harnessing the nation’s vast oil and gas resources to create viable linkages between the industry and the broader economy.

Economists flag revenue, debt risks in 2026

File format is EPS10.0.Nigeria is heading toward a difficult 2026 as widening revenue shortfalls, rising public debt, new taxes and delayed capital spending threaten to deepen economic strain, economists have said, following confirmation by Finance Minister Wale Edun that government revenues are far below target.
Edun told lawmakers this week that federal revenues for 2025 are now projected at N10.7tn, compared with an initial estimate of N40.8tn, implying a gap of about N30tn. Economists who spoke to Saturday PUNCH warn the shortfall is likely to force tighter fiscal policies next year, with implications for households, investment and social infrastructure.

“The current trajectory indicates that federal revenues for the full year will likely end at around N10.7tn, compared with the N40.8tn that was projected,” Edun said during an interactive session with the House Committees on Finance and National Planning. He attributed the shortfall largely to weak oil and gas receipts, including underperformance in petroleum profit tax and company income tax, alongside gaps in non-oil revenue collection.

The revenue miss reflects overly optimistic budget assumptions. Nigeria’s 2025 budget was based on crude oil production of 2.06 million barrels a day at 75 dollars a barrel, but output has consistently ranged between 1.5 million and 1.7 million barrels a day, while prices have mostly traded between 60 dollars and 65 dollars, occasionally nearing 70 dollars.

Former Zenith Bank Chief Economist Marcel Okeke said the divergence between assumptions and outcomes undermines earlier claims by the government that revenue targets had already been met.

“President Tinubu, in September, said that they had met their targets while projecting a decision in August. Now, in December, the Minister of Finance and Chairman of the Economic Council is providing an update on the current status,” Okeke said. “This raises a question: which source should Nigerians believe? The latter seems more credible, especially when considering budget assumptions.”

Okeke also pointed to insecurity as a drag on economic activity and revenue generation. “Public and commercial activities in affected areas have been largely disrupted, which limits government revenue and economic growth,” he said.

“The government, therefore, faces pressure to generate funds through taxation. To this end, an agreement or memorandum of understanding with France is being pursued to optimise revenue collection.”

Economist Paul Alaje warned that the shortfall could reverse recent gains in debt-service-to-revenue ratios. “Chances are really very high that there may be a resurgence of debt service to revenue, as a N30tn revenue gap means a lot,” Alaje said in comments to News Central on Thursday. “Now, what should we do when we have this?”

Alaje said the options are limited: borrowing abroad, which could take time and put pressure on the naira, or expanding domestic borrowing through bonds and treasury bills, which risks crowding out private investment and employment. He also flagged the link between higher interest rates and weakening investor confidence.

Despite earlier assurances from President Bola Tinubu that domestic borrowing had ended, the Senate in November approved a request by the administration to borrow N1.15tn from the local debt market to finance the 2025 budget deficit.

In September, Tinubu had struck a more optimistic tone. “The economy is stabilised; nobody is trading pieces of paper for exchange rates anymore. We are going up,” he said.

“Today I’m standing before you, and I can brag that Nigeria is not borrowing a dime from local banks. The revenue – we have met our target of revenue for the whole year; we met it in August. Non-oil.”

Former Crescent University Vice Chancellor Sheriffdeen Tella, who questioned why the government is planning such large deficits. “You need to borrow N30tn, so provisions for borrowing have been made. That is the implication of what you are saying,” Tella said. “I don’t understand why we should be facing such a huge deficit. If you are thinking of N30tn, this outgoing year generated more than that, so why go back?”

Tella said inefficiencies in tax collection and borrowing before the budget implementation point to weak fiscal planning. “The N10tn figure seems intended simply to justify further borrowing,” he said.  “They have even started requesting loans before implementing the budget. A budget is only an estimate; it does not reflect actual receipts.”

“Looking at past borrowing for 2025, we cannot see any positive impact because the budget was not executed,” he added. “So where did the loans go? Where is the borrowing directed? Unfortunately, the effects are unclear.”

Economist Illias Aliyu said the consequences of persistent borrowing will ultimately fall on Nigerians, particularly through reduced spending on development projects.

“We do not have a quality fiscal deficit,” Aliyu said. “When President Tinubu claimed he had met all revenue expectations, many of us were sceptical. Yet borrowing continued, which is troubling. The implication is that Nigerians will ultimately bear the burden.”

Aliyu said rising debt-service costs are squeezing capital expenditure. “Debt servicing is an obligation that must be met, including salaries and recurrent expenditures,” he said. “Indeed, about 70 per cent of capital projects have been rolled over to 2026.”

“Starting capital expenditure as late as October is detrimental,” he added. “The negative impact is clear: social infrastructure suffers, and overall, this government lacks the fiscal discipline expected, especially when compared to other governments handling multi-billion-dollar budgets.”

Nigeria’s debt burden has risen sharply under Tinubu. Government expenditure increased from N6tn to N34tn, while debt servicing climbed from N7tn to N12tn over the past two years. Total public debt stood at N152tn as of June 2025, according to official data.

The pressure is set to intensify. The government plans to borrow N17.89tn in 2026, a 72 per cent increase from 2025, to finance a widening budget deficit, raising concerns about debt sustainability and rising financing costs.

In an effort to boost revenue, the administration has passed the Nigeria Tax Act, 2025, consolidating multiple tax laws into four acts to broaden the tax base. The Federal Inland Revenue Service has also signed a memorandum of understanding with France’s Direction Générale des Finances Publiques to improve tax administration, stressing that the agreement does not grant France access to Nigerian taxpayers’ data.

Oando organises seminar for law students

Oando PlcOando Plc has convened law students from six Nigerian universities for its 2025 Legal Seminar, a 14-year initiative it described as one of its most consistent capacity-building platforms for emerging legal talent.
In a statement on Friday, Oando said the mentorship-driven forum brought together students from the University of Lagos, Obafemi Awolowo University, Lagos State University, Olabisi Onabanjo University, Rivers State University and Afe Babalola University, with a focus on equipping them with practical, market-relevant insights often absent from traditional legal curricula.

The seminar, themed ‘The 21st Century Lawyer: Keys to Building a Successful Legal Career’, featured contributions from senior practitioners in corporate law, private practice and technology law, with discussions centred on the intersection of law, business and industry.

Opening the session, Oando’s Chief Legal Officer, Efuntomi Akpeneye, said the company deliberately shifted the programme towards mentorship to bridge the gap between academia and commercial practice.

“We started this seminar to share practical knowledge across legal, energy, tax and finance. Today’s shift to mentorship for students is deliberate. Think like a business partner. Let the client’s pain be your pain. That is how you become indispensable,” she said.

Partner at Banwo & Ighodalo, Stella Duru, urged students to prioritise professionalism and discipline as key differentiators in the legal profession. “Law is a lifelong journey of learning and adaptation. Your network, professionalism and dedication will define how far you go,” she added.

Also speaking, Senior Associate at Aluko & Oyebode, Adeleresimi Adeleye, encouraged students to position themselves for a more globalised legal market, adding, “Specialised knowledge is no longer optional. If you want cross-border relevance, your skills, your language capability and your professional identity must reflect that ambition.”

From a corporate perspective, the Managing Director of Oando Energy Resources, Ainojie ‘Alex’ Irune, said legal training provides a strong advantage in commercial environments. “A law background gives you an undue advantage in commercial settings. The world is changing fast; the choices you make now will determine your relevance in the years ahead,” he noted.

The seminar also examined the growing impact of artificial intelligence and digital tools on legal practice. Leading a session on legal technology, Partner at BOC Legal, Rotimi Ogunyemi, said while AI would transform aspects of legal work, human judgement remained critical.

“AI will reshape research and drafting, but it cannot read a room or exercise ethical judgement. Human plus AI will always outperform human alone,” he submitted.

According to the statement, the event ended with a fireside chat involving Oando’s in-house counsel and internal business partners, including the Deputy Manager, Projects, Procurement and Operations, Aniekan Okon; Asset Manager, Oando Energy Resources, Oluwaseyi Fowora; and Non-Oil Commodities Lead, Oando Trading, Olusegun Oyewole. It was moderated by the Legal Advisor, Oando Trading, Isi Abulime.

The company said the seminar reinforced its commitment to talent development by bridging the gap between legal education and professional practice through mentorship, operational exposure and the transfer of institutional knowledge.

CBN pockets N192m from 82 BDC licensees

CBN Governor, Olayemi Cardoso. Photo: CBN / XThe Central Bank of Nigeria may have earned at least N192m in non-refundable fees from the 82 Bureau De Change operators who have just secured final licences under the revised regulatory framework,
The amount is based on the fee schedule in the May 2024 Regulatory and Supervisory Guidelines for Bureaux De Change Operations in Nigeria and the list of approved operators released by the Bank on December 8, 2025.

In a recent press statement, the CBN announced that it had granted final licences to 82 BDCs, effective November 27, 2025. “The Central Bank of Nigeria, in exercise of its powers under the Banks and Other Financial Institutions Act (BOFIA) 2020 and the 2024 Guidelines, has granted final licences to 82 Bureaux De Change to operate with effect from November 27, 2025,” the statement read.

The list shows that two of the firms are Tier 1 operators, while the remaining 80 are Tier 2. The tier assigned to each operator determines the amount it must pay as application and licence fees in addition to its minimum capital requirement.

Section 7.0 of the 2024 guidelines sets the non-refundable application fee for a Tier 1 BDC at N1m and the non-refundable licence fee at N5m. For Tier 2 BDCs, the application fee is N250,000, represented in the document as N0.25m, while the licence fee is N2m.

Using these official figures, the two Tier 1 operators will together pay N12m to the CBN. Their combined application fees amount to N2m, calculated as N1m each for the two operators. Their combined licence fees amount to N10m, made up of N5m each.

For the 80 Tier 2 operators, the combined application fees come to N20m. This is obtained by multiplying the N250,000 application fee by 80, giving N20m. The total licence fees for Tier 2 BDCs amount to N160m, calculated by multiplying N2m by 80.

When the Tier 2 application fees of N20m are added to the Tier 2 licence fees of N160m, the total for that category is N180m. Adding the N12m due from Tier 1 operators to the N180m due from Tier 2 operators gives an overall fee income of N192m for the CBN from this first batch of 82 approvals.

The calculation aligns with the fee levels stated in the guidelines and the number of operators in each category published by the Bank. The newly licensed Tier 1 BDCs are Dula Global BDC Ltd and Trurate Global BDC Ltd, according to the statement from the CBN.

The Tier 2 group comprises 80 firms, including Abbufx BDC Ltd, Arctangent Swift BDC Ltd, Corporate Exchange BDC Ltd, Greengate BDC Ltd, Hazon Capital BDC Ltd, Journey Well BDC Ltd, Masters BDC Ltd, Simtex BDC Ltd, Topgate BDC Ltd, Travellers Choice BDC Ltd, Victory Ahead BDC Ltd, and others spread across the country.

The non-refundable fees are distinct from the new minimum capital thresholds introduced under the reforms. The FAQs issued by the CBN state that Tier 1 BDCs must have a minimum capital of N2bn, while Tier 2 operators are required to hold N500m.

The capital must be deposited and verified before promoters can progress to final licensing, in line with the multi-stage approval process set out in the guidelines. Under the new structure, Tier 1 BDCs are permitted to operate nationwide, open branches, and appoint franchisees, subject to CBN approval.

Tier 2 BDCs can only operate in one state or the Federal Capital Territory and may establish up to five branches in their state of operation with the Bank’s consent. The CBN said only BDCs listed on its website are authorised to operate and warned that running a BDC business without a valid licence is an offence under Section 57 of the Banks and Other Financial Institutions Act 2020.

The bank also explained in its FAQs that the reforms are intended to improve access to foreign exchange for retail users, strengthen the financial sustainability of operators, and curb money laundering and other illicit financial flows in the foreign exchange market.

With the first 82 operators now fully licensed and integrated into the new regime, the central bank is expected to continue updating the list as more applicants meet the capital, governance, and compliance conditions.

“While the CBN will continue to update the list of Bureaux De Change with valid operating licences for public verification on our website, the Bank advises the general public to avoid dealing with unlicensed Foreign Exchange Operators,” the CBN said in its recent statement.

FCMB Group set for N400bn capital raise

FCMBThe shareholders of FCMB Group Plc have approved the plan to increase the company’s fresh capital raise of up to N400bn.
The approval was given during an Extraordinary General Meeting recently.

Saturday PUNCH reports that FCMB Group, in its third-quarter report filed with the Nigerian Exchange Limited, affirmed that its banking subsidiary will be recapitalised ahead of the 2026 deadline, saying, “We have successfully concluded our public offer and are on track to complete the minority subsidiary sale by the end of December.

“Subject to CBN capital verification (currently ongoing), shareholder approval at the EGM, and the required regulatory consents, we are positioned to deliver the N500bn capital target ahead of the March 2026 deadline for our banking subsidiary, FCMB Limited.”

Speaking at the EGM, according to a statement, the Group Chief Executive Officer, Ladi Balogun, expressed profound gratitude to shareholders for their support and emphasised the strategic importance of the capital raise.

He said, “The additional capital will be deployed to strengthen our capital adequacy ratio and accelerate growth. We will invest in human capital and technology, support our international expansion, and reduce high-cost deposits. We project our earnings per share to grow by over 50 per cent on average over the next two years. This positions FCMB to outperform the market while delivering stronger dividends and shareholder returns.

“With the capital adequacy ratio projected above 20 per cent, our ability to pay dividends will improve significantly. Shareholders can expect a steady rise in dividends per share, reflecting the bank’s growth trajectory and enhanced returns.”

The shareholders of FCMB Group also passed other resolutions, including acceptance of oversubscription from the 2025 Public Offer of the Group’s shares, up to the limit prescribed by the Securities and Exchange Commission and subject to regulatory approvals. This leverages the strong investor demand, reflecting confidence in the Group.

FCMB Group’s issued share capital is increased from N30,002,169,782.50 divided into 60,004,339,565 ordinary shares of 50 kobo each by the creation and addition of the number of ordinary shares that will be required to give effect to the capital raise. The new ordinary shares shall rank pari passu in all respects with the existing ordinary shares of the company.

With a diversified subsidiary portfolio and strong financial performance, FCMB has a forward-looking digital strategy and an impact-focused purpose. It is poised to make a significant contribution to Nigeria’s ambitious goal of achieving a $1tn economy.

Global oversupply leaves Nigerian crude unsold

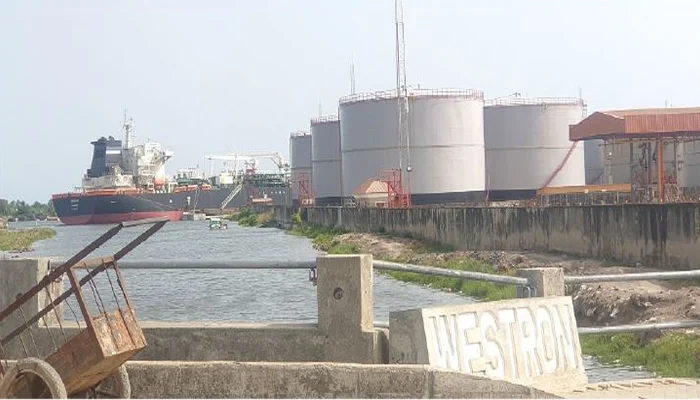
Crude oilNigerian crude oil sellers are struggling to find buyers on the global market, even as the Dangote Petroleum Refinery recently cried out over the low supply of the feedstock locally.
According to a Reuters report on Thursday, West African crude oil sellers are struggling to find buyers for up to December 26- and January-loading cargoes due to stiff competition from plentiful and cheaper alternative supplies.

About 20 million barrels of Nigerian oil for December and January loading remained unsold by Thursday, according to two traders who spoke with Reuters.

This comes as the Dangote refinery recently said it was importing heavily from the United States, Ghana, and other African countries due to a lack of sufficient supply from local oil producers.

According to the Reuters report, the amount of unsold Nigerian and Angolan crude, analysts said, is a symptom of a wider oil market surplus. This drove selling on the international futures market, pushing Brent crude below $60 per barrel to its lowest level since May this week.

“The overhang of West African cargoes partly reflects the broader global crude supply surplus emerging in Q1,” said Victoria Grabenwoger of analytics firm Kpler.

It was reported that “approximately 20 million barrels of Nigerian oil for December and January loading remained unsold by Thursday, according to two traders, while Angola’s December-January programmes still had as many as five to six cargoes available.”

These cargoes have reportedly slowed the start of the trading cycle for February cargoes, even though Angola’s loading schedule and term nominations have already been released.

The report added that such a large amount of unsold oil is unusual, especially for the current month, given that the West African trade cycle is typically closer to two months ahead.

Estimates for both countries’ overhang were as high as 40 million barrels earlier this week. “Current market softness appears to be partly seasonal and partly due to shifting buying patterns in response to freight costs and alternative supply options,” said OilX analyst Francisco Gutierrez, adding that Angolan January trade is 20 per cent behind its long-term average pace because the world’s biggest commodities buyer, China, has switched to cheaper or nearer alternative grades.

Supplies from the Middle East are said to be displacing medium and heavy West African grades in Asia, as lowered official selling prices in January, and shorter voyages give those grades a competitive edge, the analysts were quoted as saying.

India’s oil imports from Russia have remained resilient despite tightening Western sanctions, displacing medium-heavy density West African crudes, while light- to medium-density West African grades are struggling to compete with supplies from Argentina and Brazil, two traders stated.

“Nigeria has also been left to market more oil because of reduced imports by Africa’s largest oil refinery, the 650,000-barrel-per-day Dangote plant, which will in January undergo maintenance,” Kpler’s Grabenwoger said.

However, during a media briefing on Sunday, the President of the Dangote Group, Alhaji Aliko Dangote, complained about low crude supply despite the domestic crude supply obligation under the Petroleum Industry Act. Dangote said the refinery had been importing crude oil from various countries in order not to run out of feedstock.

Asked if the naira-for-crude deal had solved his challenge of low crude supply, he retorted, “We are not getting enough crude still; that’s why we buy from Ghana, we buy from a few African countries, and we buy from the United States. The US has been one of our major suppliers. On average, we don’t buy less than 100 million barrels from the US. The US is also a major beneficiary of our refinery,” the billionaire businessman said.

There was friction between the Dangote refinery and the Nigerian Upstream Petroleum Regulatory Commission over the domestic crude supply obligation.

In June 2024, Dangote’s deputy, Devakumar Edwin, accused international oil companies of deliberately frustrating the refinery’s access to local crude by selling above the market prices, forcing it to import crude from the United States and other countries.

The refinery also accused the NUPRC of failing to enforce the domestic supply obligations. Although the NUPRC defended its actions, the dispute lingered until the Federal Government ordered the Nigerian National Petroleum Company Limited to sell crude to Dangote in naira.

The naira-for-crude deal, which began in October 2024, boosted local fuel supply, reduced queues and contributed to price cuts. Dangote subsequently slashed petrol prices from about N1,100 per litre to N875, and later to N739. However, he has said repeatedly that the refinery still depends on imported crude to keep its operations running.

FirstBank partners UNIBEN to expand digital banking

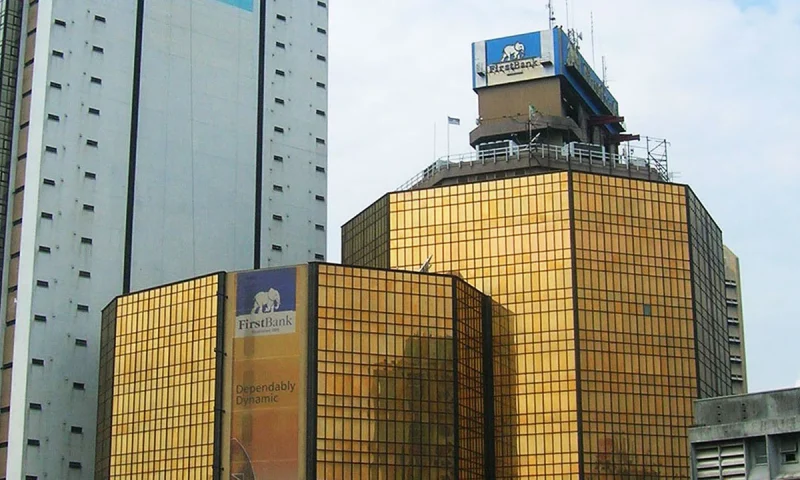
FirstBankThe Chief Executive Officer of First Bank of Nigeria, Olusegun Alebiosu, has said the bank’s Digital Xperience Centre is a step towards redefining how banking connects with education, technology, and the wider community.
He stated this at the launch of a Digital Xperience Centre, the ninth in the country, at the University of Benin recently. Alebiosu also allayed fears that the DXC, which he said is meant to improve customers’ experience, would lead to job losses.

He said the DXCs are gateways to a smarter, faster, and more personalised financial journey. The FirstBank boss said the centres are equipped with cutting-edge technology, as well as state-of-the-art self-service terminals designed to simplify transactions while ensuring top-tier security and efficiency.

He said the partnership with UNIBEN led to the creation of a hub where students, faculty, and community members can access FirstBank’s digital world. Alebiosu said the centre provides an elevated banking experience with speed and ease, designed to put the customer in control.

He said, “This digital experience centre set up by FirstBank is to take banking to the next step. It is virtually everything you see in a banking hall, and the same service. You can do everything from account opening, change of phone number, change of email, make complaints, and all others, cash withdrawal, and account statement. You can deposit money into your account.

“It will not lead to any loss of jobs. More and more people are accessing banking services, but banking platforms are not expanding as fast. This digital experience is to complement a branch. Instead of having crowds in a banking hall, frustration and complaints, people can come to the centre. It is for flexibility. The banking hall can close at 4 pm, but this one is a 24-hour operation.

“Students having examinations do not have to worry. They can come here at any time. They can be here at midnight. It is convenient and flexible. Our DXCs operate around the clock, including weekends, providing the convenience you need to bank anytime in just a few minutes.

“It embodies our commitment to Environmental, Social, and Governance principles, as it promotes financial inclusion, fosters digital literacy, and uses sustainable technology to empower underserved communities.”

The Vice-Chancellor of UNIBEN, Prof Edoba Omoregie, said the institution was pleased with the centre. He said, “We are excited and grateful to the bank. It is going to expand the scope of our staff and faculty. It will make our operations better. Ours is a big university, and the university is pleased with the bank for bringing it here.”

Petroleum regulators pledge reforms to unlock investments

SHIP OFFLOADINGPresident Bola Tinubu’s nominees for the leadership of Nigeria’s petroleum regulators on Thursday pledged sweeping reforms aimed at plugging value leakages, restoring discipline across the sector and unlocking fresh investments under the Petroleum Industry Act.
The nominee for the Nigerian Upstream Petroleum Regulatory Commission, Oritsemeyiwa Eyesan, and her counterpart at the Nigerian Midstream and Downstream Petroleum Regulatory Authority, Saidu Mohammed, made the commitments during their screening by the Senate at Room 117 shortly after plenary.

Both nominees told lawmakers that digitisation, strict contract enforcement, credible data management and accelerated gas development would be central to their leadership, as Nigeria seeks to reposition its oil and gas industry amid declining revenues and global energy transition pressures.

Eyesan, who is slated to head the upstream regulator, said weak data integration and heavy reliance on manual processes were costing the country enormous value in an industry that is rapidly becoming digital worldwide.

“We are still largely manual, while the world is moving at jet speed. Without digitisation and real-time data, you cannot truly understand what you are regulating, and you will continue to lose money,” she said, stressing that effective oversight depends on accurate numbers, asset integrity monitoring and transparent systems.

She told the committee that collaboration between regulators, operators and policymakers would be key to addressing long-standing bottlenecks in the upstream sector. “We must collaborate with stakeholders, identify our pain points, and address them collectively. That is how we move the needle forward,” Eyesan added.

The NUPRC nominee assured senators that she would fully deploy the Petroleum Industry Act as a regulatory tool to attract fresh investments and ensure Nigeria remains competitive in the global energy market, describing the law as a “valuable document” whose gains depend on proper implementation.

A graduate of Economics from the University of Benin, Eyesan spent nearly 33 years at the Nigerian National Petroleum Company Limited and its subsidiaries, retiring as Executive Vice President, Upstream.

She highlighted her role in resolving disputes with international partners, restoring investor confidence during divestment threats, and facilitating multi-billion-dollar deep offshore investments.

She also recalled signing Nigeria’s first non-associated gas development contract and contributing to an increase in crude oil production from about 1.3 million barrels per day to 1.8 million barrels per day during her tenure.

“Having worked as an operator and participated in resource development, I believe I have the competence to regulate the industry and ensure we maximise the enormous opportunities before us,” she told the committee.

On his part, Mohammed, the nominee for the midstream and downstream regulator, placed emphasis on restoring discipline to Nigeria’s gas and petroleum supply systems through strict enforcement of contracts and quality standards.

“Gas is not a favour; it is a commodity. It must be sold based on enforceable contracts from the producer to the transporter and the end-user,” he said, arguing that weak contractual frameworks had contributed to persistent gas shortages, particularly in the power sector.

He noted that uninterrupted gas supply to some power plants was only possible where contracts existed, and obligations were clearly defined, adding that enforcing the Gas Network Code would help stabilise the system and rebuild investor confidence.

Mohammed also warned against neglecting domestic refining and processing capacity, cautioning that failure to protect local value could see the sector suffer the same fate as Nigeria’s once-thriving textile industry.

While backing exports, he said domestic needs must come first to guarantee energy security. The NMDPRA nominee pledged to revive pipeline transportation of petroleum products, attract billions of dollars in investments for gas processing infrastructure, and strengthen quality assurance through in-house laboratory facilities.

“You cannot enforce quality if you do not have the capacity to test and certify products yourself,” he said. Born in Gombe in 1957, Mohammed is a chemical engineering graduate of Ahmadu Bello University, Zaria, with decades of experience across the oil and gas value chain.

He has served as Managing Director of the Nigerian Gas Company and Kaduna Refining and Petrochemical Company, as well as Group Executive Director and Chief Operating Officer, Gas and Power, at NNPC.

Reacting, the Chairman of the Senate Committee on Petroleum Resources (Downstream), Senator Sumaila Kawu, said the screening was taking place at a critical moment for the country, noting that boosting energy production and efficiency was central to Nigeria’s economic recovery.

He disclosed that further engagements with the nominees would continue into January to deepen legislative–regulatory collaboration. The Senate is expected to consider the committee’s report in the coming days and move towards confirming the nominees, a step that would mark a new phase in the regulation of Nigeria’s oil and gas industry under the Tinubu administration.

The nominations followed the resignation of the pioneer chief executives of both agencies, Gbenga Komolafe of the NUPRC and Farouk Ahmed of the NMDPRA, who were appointed in 2021 after the Petroleum Industry Act came into force.

W’Bank to approve $500m loan for Nigeria today

World-Bank

The World Bank is set to approve a $500m loan to Nigeria on Friday (today) as part of efforts to expand access to finance for micro, small and medium enterprises across the country.

The proposed facility, titled the Fostering Inclusive Finance for MSMEs in Nigeria (FINCLUDE) Project, aims to mobilise private capital and promote innovative financial products for small businesses, according to information obtained from the World Bank.

Negotiations on the loan are ongoing, and approval by the World Bank Group’s board is expected on Friday. The approval, expected on December 19, 2025, will see the World Bank commit $500m to the project out of an estimated total cost of $2.39bn.

Of the World Bank financing, $400m will be provided by the International Bank for Reconstruction and Development, while $100m will come from the International Development Association.

The Federal Government will be the borrower under the arrangement, with the Development Bank of Nigeria serving as the implementing agency with overall responsibility for managing the funds. The remaining $1.89bn required for the project is expected to be provided by commercial lenders as unguaranteed financing.

According to the World Bank, the FINCLUDE project will leverage the platforms of the Development Bank of Nigeria and its subsidiary, Impact Credit Guarantee Limited, to deepen credit access for MSMEs.

“The proposed FINCLUDE Project leverages the platforms of the Development Bank of Nigeria and its subsidiary, the Impact Credit Guarantee Limited, to drive inclusive MSME finance,” a document from the World Bank read. “Through these catalytic institutions, the project will deploy a package of complementary, inclusive, and innovative instruments tailored to the diverse needs of MSMEs in Nigeria.”

The World Bank described DBN as “a partner well known to the World Bank with high implementation capacity and a proven track record in designing and executing complex, innovative projects,” noting that its role would be central to the success of the intervention.

The project is structured around three main components. These include the provision of inclusive and innovative MSME finance products, the de-risking and mobilisation of private capital through partial credit guarantees, and technical assistance aimed at modernising and digitising Nigeria’s MSME finance ecosystem.

Under the first component, the World Bank said the project would provide Tier 2 subordinated capital to eligible financial institutions and support the establishment of an MSME investment fund to deliver equity and long-term debt financing to small businesses. The bank said this approach would help “crowd-in private capital, test market innovations and promote financial sustainability” within the MSME segment.

Also, the project will offer targeted technical assistance to strengthen the capacity of financial institutions, improve regulatory oversight and modernise the MSME finance value chain linking DBN, lenders and entrepreneurs.

In its appraisal report, the World Bank highlighted Nigeria’s ongoing economic reforms, describing the country as being “in a critical transition.” It noted that the removal of fuel and foreign exchange subsidies, alongside the unification of exchange rates, had begun to stabilise the economy and restore investor confidence.

“These reforms have improved fiscal space, enhanced FX liquidity, and eased inflation to 18 per cent as of September 2025,” the report stated, adding that growth prospects were strengthening, with the International Monetary Fund projecting 3.9 per cent real GDP growth in 2025.

Despite these improvements, the World Bank warned that access to finance remained uneven, particularly for MSMEs, women and the agriculture sector. It noted that agriculture accounted for just over five per cent of total bank credit in 2024, while high interest rates and shallow credit penetration continued to constrain lending to smaller enterprises.

If approved on Friday, the FINCLUDE project will add to Nigeria’s growing portfolio of World Bank-supported programmes. As of June 30, 2025, Nigeria’s external debt stood at $46.98bn, according to the Debt Management Office.

The World Bank Group remains Nigeria’s largest single creditor, accounting for $19.39bn of the total, comprising $18.04bn from the IDA and $1.35bn from the IBRD. This represents 41.3 per cent of the country’s external debt, underscoring the bank’s dominant role in financing Nigeria’s development initiatives.

The PUNCH earlier reported that the World Bank loans to Nigeria between 2023 and 2025 are projected to reach $9.65bn by the end of this year as fresh approvals, ongoing negotiations, and disbursements gather pace across key sectors.

The amount covers International Bank for Reconstruction and Development and International Development Association loans only, according to an analysis of data on the bank’s website by The PUNCH. When grants are added, total World Bank support rises to about $9.77bn within the three-year window.

The International Bank for Reconstruction and Development provides loans on commercial or near-commercial terms to middle-income and creditworthy low-income countries, while the International Development Association offers highly concessional loans and grants to the world’s poorest nations.

The PUNCH also reported that Nigeria’s stock of World Bank International Development Association loans rose to $18.5bn, making it the largest IDA borrower in Africa and the third-biggest in the world.

Fresh data from the IDA’s unaudited financial statements for the third quarter of 2025 confirmed that the country has maintained the ranking it first attained in 2024, when it climbed to third place after overtaking India. The country was the fourth-largest borrower in 2023.

According to the report, Nigeria’s exposure increased from $17.1bn in September 2024 to $18.5bn in September 2025, representing a rise of $1.4bn or 8.2 per cent. The increase reflects the country’s heavier reliance on concessional financing to plug infrastructure gaps, stabilise its reform programme, and support social spending amid volatile oil earnings.

Economists warn that the rising loan pipeline, while potentially beneficial for long-term development, could deepen fiscal pressures if not matched with stronger domestic revenue mobilisation and prudent expenditure management.

Lagos-based economist, Adewale Abimbola, reacting to the rising World Bank commitments to Nigeria, said loans from multilateral institutions such as the World Bank are largely concessionary, with interest rates typically below market levels and longer repayment tenors.

He noted that the critical question is not whether Nigeria should be borrowing, but whether the loans are structured and deployed effectively. “If it’s concessionary and tied to viable projects with medium-term revenue prospects, I don’t think it’s a bad idea,” Abimbola explained. “Borrowing isn’t bad; what matters is utilisation.”

He stressed that the economic impact of such loans depends on how well they are channelled into projects that can generate sustainable growth, strengthen revenue, and improve public services over time.