Sterling Bank keeps NPL below CBN threshold for decade

Sterling Bank keeps NPL below CBN threshold for decadeSterling Bank’s non-performing loan ratio has remained largely stable over the past decade, rising marginally from 4.80 per cent in the first quarter (Q1) of 2016 to 4.93 per cent in Q1 2026, while staying below the Central Bank of Nigeria’s five per cent prudential threshold.

Sterling Bank’s ratio remained far lower than the industry’s performance of eight per cent to nine per cent in Q1.

Bad loans in Nigeria’s banking sector stood at 8.03 per cent in January 2026. The figure, contained in the CBN’s January 2026 Economic Report, showed that the industry’s non-performing loans ratio rose by 0.52 percentage point from 7.51 per cent in December 2025.

It also remained above the CBN’s prudential threshold of five per cent, indicating a further deterioration in asset quality across the banking industry despite the apex bank’s insistence that the sector remained resilient.

The report said, “Following the bank’s loan reclassification after the withdrawal of forbearance, the non-performing loans ratio rose by 0.52 percentage point to 8.03 per cent compared with the level in the preceding period and was above the 5.00 per cent prudential threshold.”

The average (NPL) ratio for the Nigerian banking sector reached 9.85 per cent by February.

The CBN warned that a stubborn rise in non-performing loans could impair asset quality and weaken banks’ balance sheets, thereby posing systemic risk.

It recommended deepening “the operational integration of the GSI framework across all financial institutions to enhance loan recovery efficiency and credit discipline.”

The CBN also recommended strengthening credit discipline and reducing NPLs by fully integrating the Global Standing Instruction framework to boost loan recovery efficiency.

MAN warns inflation won’t ease without reforms

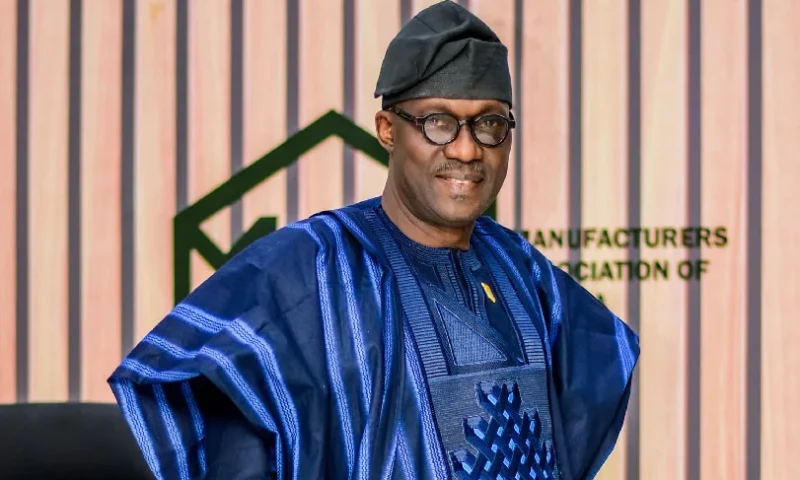
The Manufacturers Association of Nigeria has renewed its call for coordinated structural reforms to address inflation, improve productivity and strengthen the competitiveness of the country’s manufacturing sector, as it looked ahead to the second half of 2026 following disruptions caused by the Middle East conflict.

The association made the call against the backdrop of the latest National Bureau of Statistics data, which showed that Nigeria’s headline inflation eased marginally to 15.91 per cent in June 2026 from 15.93 per cent in May. However, food inflation accelerated on a month-on-month basis, driven by higher prices of fresh pepper, tomatoes, crayfish, beef, garri, yams and other staple foods.

The PUNCH earlier reported that members of the organised private sector welcomed the slight decline in the inflation rate for June 2026 but warned that inflation remained in double digits and prices were still too high for businesses and consumers.

In his remarks for the April-June edition of MAN News obtained by this publication, the Director-General of MAN, Segun Ajayi-Kadir, observed that the renewed increase in inflation during the quarter highlighted the fragility of Nigeria’s economic recovery as higher food prices, energy costs, transportation expenses and exchange rate pressures continued to raise production costs and weaken consumers’ purchasing power.

“MAN has consistently maintained that addressing inflation requires coordinated structural reforms that improve productivity, strengthen infrastructure, enhance security in agricultural and industrial communities, and stabilise the foreign exchange market,” Ajayi-Kadir stated.

Meanwhile, Ajayi-Kadir noted that the association remained committed to pursuing policies that would enhance industrial competitiveness despite economic headwinds in the first half of the year.

He said, “As we enter the second half of the year, our priorities remain firmly focused on advancing policies that improve competitiveness, encourage investment, expand local production, deepen exports, and position Nigeria as Africa’s industrial hub and the preferred manufacturing destination.”

He noted that the second quarter witnessed increased business and government activities after a slow start to the year but was affected by insecurity across parts of the country and the impact of the ongoing conflict between the United States and Iran in the Middle East.

Ajayi-Kadir reported that the association advocated the recapitalisation of the Bank of Industry, the creation of additional concessionary lending windows for manufacturers, lower import costs for industrial machinery and essential raw materials, and long-term development finance to support investment and expansion.

He expressed concern over the continued decline in credit to manufacturers, warning that industrialisation would remain constrained if productive enterprises could not access affordable financing.

He also reaffirmed MAN’s support for tax reforms that modernise tax administration and improve revenue generation but opposed the retroactive application of the 2025 Nigeria Tax Laws, noting, “Our position remains unchanged. We support reforms that modernise tax administration, improve revenue mobilisation, and strengthen fiscal sustainability. At the same time, successful reform depends on transparent implementation, predictable policies, and continuous stakeholder engagement.”

The MAN DG further urged the Federal Government to address the unresolved foreign exchange forward obligations owed to some manufacturers, describing the issue as a breach of valid contracts that had continued to weaken the financial position of affected companies.

He said the association also intensified advocacy for greater local raw material utilisation through collaboration with the Raw Materials Research and Development Council and the Nigeria Customs Service to deepen backward integration and reduce dependence on imported industrial inputs.

Ajayi-Kadir added that MAN remained optimistic that continued collaboration between the government and the private sector would strengthen ongoing economic reforms and support Nigeria’s industrial transformation.

Wema Bank’s assets surge 13-fold to N5.23tn in decade

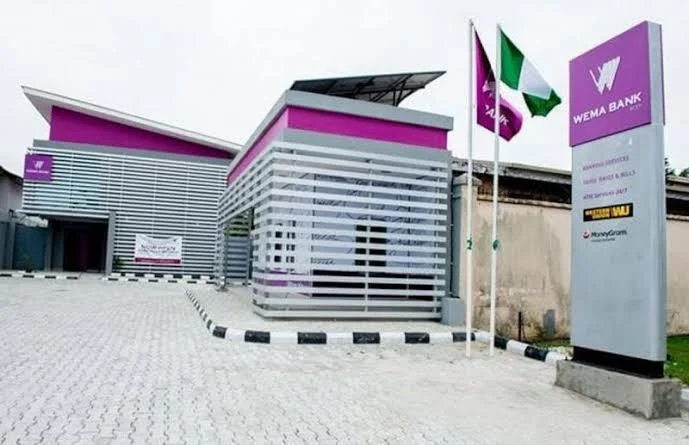
Wema bankWema Bank has reported measurable growth over the last decade, growing its assets 13-fold over the period.

According to The PUNCH’s findings, the size of the lender’s assets have jumped 1,185 per cent to N5.23tn between the first quarter (Q1) of 2016 and the corresponding period of 2026.

The monetary value of Wema Bank’s asset size rose from N407bn in 2016 to N5.23tn in 2023.

The sharp increase in asset size over the 10-year period means Wema Bank now manages more than 13 times the resources it held a decade ago, significantly strengthening its financial capacity.

The expansion has important implications for the lender’s operations and the broader economy.

A larger asset base gives Wema Bank greater capacity to extend credit to households and businesses, finance infrastructure and corporate projects, absorb economic shocks, and comply with tighter regulatory capital requirements. It also enhances the bank’s competitiveness against larger rivals, improves its ability to attract investors, and provides a stronger platform for future expansion.

Analysts say the sustained growth underscores the success of the bank’s digital-first strategy, anchored by its ALAT platform, as well as its “focus on retail banking, small and medium-sized enterprises, and prudent balance sheet management,” said a Lagos-based financial expert, Kabby Umunna.

NCC, African Regulators Drive Stronger Collaboration For Smarter Digital Governance

The Nigerian Communications Commission (NCC) has called for deeper collaboration among African Telecommunications and Communications Regulators to strengthen the use of data, evidence and market intelligence in driving more effective and responsive regulation across the continent.

Speaking at the Heads of Regulators Roundtable during the African Telecommunications Union (ATU) Conference of Plenipotentiaries (CPL-26) in Abuja, Dr. Maida said communications regulation has become increasingly central to economic growth, digital transformation, and national development across Africa.

He observed that although regulators operate within different market environments and legal frameworks, they face many common challenges, including infrastructure development, cybersecurity, affordability, satellite services, resilience of networks, and the rapid emergence of artificial intelligence technologies.

The NCC Chief Executive noted that exchanges among regulators often reveal shared experiences and lessons that can help institutions address complex policy and regulatory issues more effectively. He stressed the need to make such knowledge-sharing more deliberate, systematic, and beneficial to regulatory authorities across the continent.

He noted that “Very often, the challenge one regulator is trying to solve has already been encountered, in one form or another, by a colleague elsewhere on the continent.”

The EVC described the event’s theme, “Building Africa’s Network Intelligence Ecosystem for Evidence-Based Regulation,” as both timely and highly relevant to the future of communications regulation on the continent.

“It gives us an opportunity to consider how better use of data, evidence and market intelligence can strengthen regulatory decisions, and how African regulators can learn more systematically from one another,” he explained.

While chairing the roundtable, Rimini Makama, NCC’s Executive Commissioner, Stakeholder Management, stated that, “developments such as broadband expansion, satellite services, artificial intelligence, cloud computing and digital public infrastructure are making communications ecosystems increasingly complex and requiring regulators to move beyond traditional regulatory approaches”.

She noted that regulators across Africa now have access to growing volumes of technical, market and consumer data, but stressed that the real challenge lies in translating this information into actionable intelligence capable of supporting better regulatory outcomes.

The Heads of Regulators Roundtable forms part of ongoing efforts by African communications regulators to promote evidence-based regulation, enhance regional cooperation and build more resilient, innovative and consumer-focused communications ecosystems across the continent.

GTCO Announces 16th Autism Conference And Free Consultations

The Guaranty Trust Holding Company Plc (“GTCO”) has announced full plans for its 16th Annual Autism Conference scheduled to hold on Monday, July 27th and Tuesday, July 28th, at the Muson Centre, Lagos. Themed “Acceptance in Action: From Family to Classroom to Workplace to Public Spaces,” the Conference, which will be followed by one-on-one family consultations by specialists, continues the Group’s commitment to advocating for Autism through access to developmental support, professional guidance, and learning opportunities for individuals on the autism spectrum and their families.

Over the years, the GTCO Autism Programme has become a leading platform for Autism advocacy and inclusion across West Africa, bringing together healthcare professionals, therapists, educators, policymakers, caregivers, and families to foster greater understanding of Autism Spectrum Disorders (ASDs). Through sustained engagement and collaboration, the programme has helped advance conversations around acceptance, accessibility, and the support systems required to improve outcomes for individuals on the spectrum.

This year’s theme, “Acceptance in Action,” reflects the need to move beyond awareness towards creating environments where individuals on the Autism spectrum are supported, and empowered at home, in school, in workplace, and public spaces. The 2026 programme will feature expert-led discussions, workshops, and free consultation sessions delivered by leading local and international specialists in developmental and behavioural sciences, covering key areas such as early intervention, behavioural therapy, communication strategies, inclusive education, and caregiver support.

In Nigeria, the conference will hold on Monday, July 27th and Tuesday, July 28th at the Muson Centre, Lagos, followed by free one-on-one family consultations with medical and developmental specialists from July 29th to August 1st at the Adeyemi Bero Auditorium, Alausa Secretariat, Ikeja. In Ghana, the programme will open with a workshop on August 4th at the University of Professional Studies, Accra, followed by free consultations at the same venue from August 5th to 8th.

Commenting on the 2026 GTCO Autism Programme, the Group Chief Executive Officer of Guaranty Trust Holding Company Plc, Mr Segun Agbaje, said: “Sixteen years ago, we set out to help families navigate a journey that too often felt isolating. Today, this programme stands as proof of what sustained commitment can achieve. This year’s theme, ‘Acceptance in Action,’ challenges all of us to move past good intentions and start making inclusion visible, in the way we design our schools, structure our workplaces, and welcome one another in public spaces.”

He added: “No single institution can build an inclusive society alone. It takes families willing to advocate, educators willing to adapt, employers willing to open doors, and policymakers willing to act. Our role is to keep bringing the right expertise and resources to the table, so that every individual on the autism spectrum has a genuine chance to participate fully and confidently in everyday life.”

Dangote Halts Petrol Sale In Dollar As Nigeria’s Heightens Imports

In a patriotic gesture to minimize petroleum price shock in the domestic market,

Dangote Petroleum Refinery has resumed the sale of Premium Motor Spirit (PMS) or petrol in naira, providing a measure of relief to marketers and consumers.

The Gantry price is fixed at N1,215/ litre.

Following a week of economic uncertainty owing to Dangote’s decision to load fuel in dollars, the refinery has fixed its new ex-depot (gantry) price to Naira, albeit at a higher cost.

The new price was revised to N1,215 per litre, representing an increase of N140 per litre, or 13.02 per cent, from the previous price of N1,075 per litre.

“Dangote Petroleum Refinery has resumed the sale of Premium Motor Spirit (PMS) in naira, providing a measure of relief to marketers and consumers,” a statement released on Wednesday read

“The gantry price is fixed at N1,215/ litre,” it added”.

After notifying clients of the new conditions on Tuesday, the refinery resumed the acceptance of orders for coastal loading.

Following an extended period of uncertainty within the downstream petroleum market due to the suspension of fuel sale in naira, which compelled several independent marketers to procure supplies from private depots, the refinery has reinstated naira-denominated pricing for truck loading.

Under the dollar pricing system Automotive Gas Oil (diesel) was set to cost $1.087 per litre, while Aviation Turbine Kerosene (ATK) was priced at $0.942 per litre. Petrol delivered via coastal deliveries was tagged at $1,044.62 per metric tonne.

At the time, the refinery notified marketers and customers that all previously issued naira-denominated Proforma Invoices and Deal Recaps for gantry and coastal transactions were no longer legitimate.

The notice, signed by the refinery’s Group Commercial Operations, read, “Following our email on the 9th of July, 2026, regarding the transition from Naira to United States Dollars, please note that all issued Naira Coastal and Gantry PFIs/Deal Recaps are now invalid, and no payments should be made against them.

Meanwhile, Nigeria’s petrol imports more than tripled last month as the country’s main refinery cut domestic supply and increasingly directed output toward export markets to maximize foreign-currency earnings.

Nigeria shipped in 18.1 million liters of the fuel per day in June, compared with 5.6 million liters in May, the Nigerian Midstream and Downstream Petroleum Regulatory Authority (NUPRC) said in a monthly report.

The Dangote Petroleum Refinery increasingly directs output to export markets to maximize foreign currency earnings. Selling products in naira domestically limits the U.S. dollars required to purchase international crude oil feedstock, driving the refinery to prioritize lucrative European and African exports.

According to figures in June, the refinery exported 466,000 metric tonnes of aviation fuel, overtaking the United States as Europe’s largest external supplier of jet fuel.

The facility has expanded its footprint across the continent, successfully exporting cargoes to countries like Côte d’Ivoire, Cameroon, Tanzania, Ghana, and Togo.

The plant’s domestic allocation under the local naira-for-crude agreement has significantly declined.

As a result, the refinery must source a greater share of its feedstock from the international market, which must be paid for in dollars.

Because the refinery struggles to convert naira revenue into the necessary foreign exchange to buy raw crude, it relies heavily on export markets to sustain its operations. Consequently, Nigeria’s domestic petrol imports have recently surged as the refinery reduces local supply according to Bloomberg.

GCR upgrades FCMB Group rating, affirms stable outlook

FCMB Group PlcGCR Ratings has upgraded FCMB Group Plc’s national scale long‑term issuer rating to A‑(NG) from BBB+(NG), while affirming the national scale short‑term issuer rating at A2(NG).

Concurrently, GCR upgraded the national scale issue ratings on the Series 1 N20.7bn and Series 2 N26bn Additional Tier 1 Subordinated Bonds to BBB(NG) from BBB‑(NG), maintaining a stable outlook across the board.

“The positive rating action on FCMB Group Plc is hinged on the improved fundamentals of the group’s core operating entity, First City Monument Bank Limited,” GCR stated in a rating announcement on Monday.

“The ratings upgrade reflects the improvement in FCMB’s capital adequacy, supported by the additional capital injection and good internal earnings generation,” the rating agency added, noting that the score also “balances the strong competitive position, adequate funding and liquidity position against the bank’s evolving risk profile”.

FCMB Group operates as a financial services holding company in Nigeria with core operations in banking and a growing footprint across non‑bank financial services, including consumer finance, investment management, and investment banking.

The group encompassed seven direct subsidiaries and three indirect subsidiaries as of 31 December 2025, with a long‑term strategy to expand its footprint across other African markets.

Addressing the structural hierarchy of the institution, GCR noted, “FCMB Group’s rating is one‑notch lower than the consolidated group, due to the subsisting structural subordination.

“This reflects the Non‑Operating Holding Company’s reliance on cash flows and dividends from the bank and other subsidiaries, which could be diverted by regulatory intervention at a time of stress,” the agency explained.

The Series 1 and Series 2 perpetual, non‑cumulative, fixed‑rate, resettable Additional Tier 1 Subordinated Bonds represent the initial tranches issued under the group’s N300bn Debt Issuance Programme. Originally raised in 2023 at a resettable fixed coupon rate of 16 per cent with no scheduled maturity date, these instruments qualify as AT1 capital under Central Bank of Nigeria approvals.

GCR noted that it applied a three‑notch differential from the bank’s senior unsecured ratings due to back‑to‑back loan agreements, contractual note subordination, deferrable interest payments, and write‑down triggers tied to a core equity tier 1 ratio dropping to 10.75 per cent or a point of non‑viability determination by the regulator.

Following recent capital infusions, the bank’s CET1 ratio strengthened from 14.3 per cent as of 31 December 2025 to 22.3 per cent by 31 March 2026. Periodic reports submitted by bond trustees indicate that coupons on both series have been serviced timely without financial covenant breaches.

Outlook metrics for the institution remain positive over the medium term. “The stable outlook reflects our expectations that the GCR core capital ratio will range between 19 per cent and 22 per cent over the next 12–18 months, on account of the bank’s conservative loan book growth,” GCR stated.

“The sustained loan book clean‑up and recovery efforts could support the asset quality metrics, although it remains vulnerable to challenges in the macroeconomic environment,” the agency added. “The funding and liquidity position is expected to remain stable, predicated on the good deposit mobilisation capacity and other funding options”.

Petrol loading resumes as depot prices climb

Petrol

Fuel marketers have resumed loading petrol and diesel from private depots after an almost one-week disruption triggered by recent price adjustments in the downstream petroleum sector.

The National Publicity Secretary of the Independent Petroleum Marketers Association of Nigeria, Chinedu Ukadike, told The PUNCH on Tuesday that private depots had resumed selling petroleum products to marketers, dismissing fears of an imminent fuel scarcity.

Although some filling stations did not dispense petrol on Monday and Tuesday, Ukadike said marketers were only being cautious because of the prevailing volatility in fuel prices, particularly amid the ongoing Middle East crisis.

He explained that depot owners temporarily suspended loading operations to adjust prices and request top-up payments from marketers who had already paid for products before the latest price increase. Ukadike, however, noted that depot owners do not refund marketers when prices fall below the amount previously paid for products.

Speaking on the Dangote Petroleum Refinery’s newly introduced dollar-for-fuel policy, Ukadike said he could not confirm whether marketers had started paying in dollars for products loaded through the refinery’s gantry in Lekki, Lagos.

“Marketers have started loading in other depots. You know, once there is a price change, they will stop and take their stock, then reset their prices around the rest of them. Then also look at the tickets they have sold before and see how they will do top-up. What we call top-up is the differential of the former price, so they can buy at the current price. These are the exercises that are ongoing. And once they are ongoing, you cannot load,” he said.

He added, “I know that Dangote has fixed its price in dollars, but no marketer has ever informed me that they have paid in dollars, especially those loading from the gantry. But for offshore loading or coastal loading, I can assure you that it will be paid in dollars. But for gantry loading, I don’t know. By tomorrow, I will confirm.”

Meanwhile, petrol loading prices rose further across major private depots in Lagos on Tuesday, with marketers paying up to N1,275 per litre amid continued uncertainty in the downstream petroleum market following the Dangote Petroleum Refinery’s transition to dollar-denominated transactions.

Depot price data obtained by The PUNCH from Petroleumprice.ng showed that loading prices in Lagos increased by N25 per litre at most depots. African Terminal, ASCON, Gulf Treasure, Integrated, Matrix, NIPCO, Pinnacle, Sahara and T.Time all raised their ex-depot prices from N1,250 to N1,275 per litre.

However, prices were mixed in other parts of the country, as some depots retained their previous rates while others recorded marginal reductions.

In Port Harcourt, Bulk Strategic and Masters retained their petrol prices at N1,265 per litre. Liquid Bulk reduced its price by N3 from N1,268 to N1,265 per litre, while Matrix cut its loading price by N15 from N1,280 to N1,265 per litre. Sigmund also sold petrol at N1,265 per litre.

In Calabar, Hong Petroleum reduced its price by N15 from N1,270 to N1,255 per litre, while Sobaz increased its loading price by N10 to N1,265 per litre.

In Warri, Matrix increased its depot price by N5 to N1,265 per litre, while Optima raised its price by N10 to N1,270 per litre. Rain Oil retained its price at N1,270 per litre, while Prudent sold the product at N1,270 per litre.

Diesel prices also edged higher at some depots. In Lagos, African Terminal, Duport, Gulf Treasure, Ibachem and Wosbab increased their diesel prices by N10 to N1,600 per litre, while Ibeto retained its price at N1,590 per litre. Integrated quoted N1,600 per litre.

In Port Harcourt, Sigmund increased its diesel price by N5 from N1,615 to N1,620 per litre, while Sahara sold the product at N1,600 per litre. In Warri, Prudent raised its diesel price by N10 to N1,610 per litre, NIPCO retained its price at N1,680 per litre, while Rain Oil sold diesel at N1,600 per litre.

The latest price adjustments highlight the persistent volatility in the downstream petroleum market following the Dangote Petroleum Refinery’s decision to sell petrol to marketers in dollars, a development that continues to influence depot prices across the country.

While loading activities at the Dangote refinery were said to be low-key, fuel importers appeared to be taking advantage of the situation, even as consumers continued to bear the burden of higher pump prices nationwide.

Industrial sector drags NGX down 0.14%

The Nigerian Exchange Limited experienced a wave of mixed sentiments during the trading week ended 17 July 2026. A sharp decline in the industrial sector effectively offset strong gains in banking equities, reflecting a broader tug-of-war between institutional portfolio rebalancing and macroeconomic headwinds.

The benchmark NGX All-Share Index depreciated marginally by 0.14 per cent to close the week at 243,462.13 points. Conversely, total market capitalisation managed to buck the downward index trend, appreciating by 0.39 per cent to settle at N157.057tn by Friday’s close.

This divergence between the ASI and market capitalisation was primarily attributed to large-scale primary market listings and capital restructuring during the week, which added weight to the total market value despite price depreciation among major equities.

A closer look at the sectoral performance revealed that a steep 6.26 per cent decline in the NGX Industrial Goods Index acted as the primary anchor dragging down the broader market index. The industrial sector continues to face severe pressure from elevated energy costs, persistent foreign exchange illiquidity affecting raw material imports, and the high-interest-rate environment, which has slowed down major real estate and infrastructure projects nationwide.

This downward pressure was further compounded by losses in the NGX Main Board Index, which fell 1.54 per cent, alongside minor pullbacks in the Consumer Goods and Oil & Gas indices. Consumer goods companies, in particular, remain squeezed by weakened disposable income among Nigerian households, forcing investors to adopt a cautious stance.

On the flip side, the banking sector put up a resilient fight against the bears. The NGX Banking Index climbed 9.30 per cent, preventing a more severe market downturn. This rally was largely driven by sustained investor appetite following strong half-year corporate earnings releases and speculative positioning around the Central Bank of Nigeria’s ongoing banking recapitalisation exercise, which has favoured tier-one institutions.

Trading volumes decline

Activity on the trading floor slowed down significantly compared with the previous week’s performance, indicating a temporary shift towards a ‘wait-and-see’ approach by institutional investors ahead of macroeconomic data releases.

Investors traded a total turnover of 2.819bn shares worth N182.499bn in 226,729 deals, representing a noticeable drop from the 3.648bn shares valued at N220.568bn that exchanged hands in the preceding week.

As has become the norm on the local bourse, the Financial Services Industry single-handedly drove the market’s liquidity, accounting for over 71 per cent of the total equity turnover volume. The sector’s dominance underscores its status as the most liquid and actively traded segment of the NGX, especially during periods of broader economic uncertainty.

Divergent price action

Market sentiment measured by price changes leaned slightly towards the bears, as the number of advancing equities dropped from 60 in the previous week to 44, signalling a tightening of market breadth.

First HoldCo Plc emerged as the standout performer of the week, leading the gainers with an impressive 38.66 per cent price surge to close at N95.95 per share. Analysts attributed this rally to robust institutional buying and positive market sentiment surrounding its strategic expansion plans.

BUA Cement Plc suffered the worst hit on the decliners’ table, shedding 18.99 per cent of its value to close at N275.60 per share. The heavy sell-off in BUA Cement heavily influenced the slump in the Industrial Goods index, as investors reacted to profit-taking and broader concerns regarding input cost inflation within the manufacturing sector.

Capital base expansion

The week also featured a significant corporate action as Sterling Financial Holdings Company Plc successfully expanded its presence on the local bourse, highlighting the ongoing capital raising trend in the financial sector.

The Exchange listed an additional 13.812bn ordinary shares arising from the company’s recent public subscription offer at N7.00 per share.

This supplementary listing officially boosted the total issued and fully paid-up shares of the financial holding company from 52.117bn to 65.929bn units.

This capital injection not only strengthens Sterling HoldCo’s balance sheet to absorb potential macroeconomic shocks but also directly contributed to the appreciation of the total NGX market capitalisation, despite the marginal drop in the All-Share Index.

Inflation moderates further

The cautious stance by investors came as Nigeria’s headline inflation slowed marginally for the first time in four months, as easing core inflation offset persistent food price pressures.

In tandem with the cooling inflation data, domestic crude oil production rose to a 74-month high, exceeding Nigeria’s OPEC quota for the second consecutive month.

Simultaneously, the CBN introduced the FX BDC Purchase Tracker to improve transparency and efficiency in the retail foreign exchange market. The centralised digital platform requires licensed Bureau De Change operators to submit foreign exchange transactions in real time.

The initiative builds on the February 2026 policy that restored BDCs’ access to the official FX market through weekly allocations of up to USD150,000 from Authorised Dealer Banks. It replaces the previously manual, delay-prone reporting framework that fostered pricing distortions, speculative hoarding, and ultimately prompted the suspension of official Dollar sales to BDCs.

The platform reinforces the apex bank’s commitment to improving transparency and accountability in the retail FX market. By enabling transaction-level monitoring, the CBN aims to eliminate practices such as round-tripping and currency diversion, while ensuring official FX allocations are deployed solely to meet legitimate retail demand. The system also provides regulators with better visibility into demand dynamics, utilisation rates, and compliance across the BDC segment.

Reacting to the development, analysts at Meristem Securities Limited stated, “We expect the FX BDC Purchase Tracker to strengthen price discovery and improve transparency within the retail foreign exchange market, thereby reducing opportunities for speculative buying and arbitrage opportunities, and gradually compressing the spread between the official and parallel market exchange rates.

“The effectiveness, however, will depend on the CBN’s consistency in enforcing compliance and penalising reporting violations. In the near term, the success of the framework will hinge on its ability to facilitate seamless adoption across dealer banks and BDCs while improving retail FX liquidity, strengthening price discovery, and fostering a more efficient and orderly foreign exchange market.”
NUPRC awards 37 oil blocks, warns against delays

NUPRCThe Nigerian Upstream Petroleum Regulatory Commission on Tuesday declared 31 companies as winners of 37 oil and gas blocks under the 2025 Licensing Round, despite what the commission described as sustained threats and pressure mounted against members of its evaluation team before the conclusion of the exercise.

The successful conclusion of the commercial bid conference marked the end of an eight-month licensing process, with the winning firms now required to pay their signature bonuses and satisfy other post-award conditions within 90 days or risk forfeiting the assets to reserve bidders.

Speaking after the commercial bid conference in Abuja, the Commission Chief Executive of the NUPRC, Oritsemeyiwa Eyesan, disclosed that officials involved in evaluating the bids faced repeated intimidation throughout the process but refused to compromise the integrity of the exercise.

She said the threats persisted until the eve of the commercial bid opening. Eyesan said, “It has been a journey… If you have been told anything contrary to the fact that this process was going to be credible and transparent, do not believe it.”

Commending members of the evaluation committee, she added, “The evaluators have worked tirelessly since June 12. They have been inundated with calls and with threats, serious threats, but they stood their ground. Up until yesterday, we were still threatened, but we stood our ground to say that the times have changed. Nigeria is really open for business.”

She said President Bola Tinubu had mandated the commission to ensure a credible process and thanked the evaluators and observers from the Nigeria Extractive Industries Transparency Initiative for supporting the exercise.

The commission announced that 31 companies emerged successful after 143 companies submitted about 200 bids for 37 oil and gas blocks out of the 50 assets offered during the licensing round.

The successful companies include SSonic Petroleum Limited, CFP Pipeline and Flowlines, Dutchford E&P Limited, Attabanson Global Company Limited, Rosem Energy Limited, Pivot-GIS Limited, Network E&P, Asharami, LexOil, BVOF, Gupsco Energy Limited, Saratoga, Volante, Concept-Reel Petroleum Services Limited, Clinton Oil Field, Nuway Oaklane Limited, Ramec Italia.

Others are Blueridge E&P, Up Energies Limited, AYM Shafa, Blackrock Holdings Limited, Funtay Integrated Business Limited, Riparian Development and Production Limited, Nikstallis, Stardeep Petroleum, Dakoda & U Limited, Southborne Oil and Gas Limited, Lanaka Petroleum, Highban Resources Limited and Eyre Energy Limited.

The commission explained that the successful companies had emerged only as preferred bidders and would receive Petroleum Prospecting Licences after meeting all statutory conditions under the Petroleum Industry Act.

Eyesan urged the winners to immediately commence the post-award process. She said, “These firms will only be presented final awards after the payment of the appropriate signature bonus and the approval of the Minister of Petroleum Resources in line with the Petroleum Industry Act, 2021.”

She warned that failure to fulfil the post-award conditions within 90 days would invalidate the awards, allowing the commission to invite reserve bidders.

The commission explained that the commercial bid process was designed to eliminate human interference through an automated weighted scoring system. Officials said technical evaluations had been completed before the commercial bids were opened publicly, while no one, including members of the evaluation team, had prior access to the commercial bids.

“The weighted score is 40 per cent. All these things are automated. The computer calculates everything. Nobody is using a pen to write any figures. This demonstrates the transparent, efficient and robust process built into this licensing round,” the commission stated.

Meanwhile, the Minister of State for Petroleum Resources (Oil), Senator Heineken Lokpobiri, said the Petroleum Industry Act had ended the discretionary allocation of oil blocks in Nigeria. “The PIA, unfortunately for some people, has prevented discretionary allocation of oil blocks,” he said jokingly.

He stressed that the law guarantees fairness and credibility, assuring investors that no one knows the content of commercial bids before they are officially opened. Lokpobiri also warned successful bidders against treating licences as speculative assets.

“In the past, I have seen people go round conferences across the world carrying licences and looking for partners who never came. Those days must be over. The licences issued today must translate into actual field development and production,” he said.

Also speaking, the Minister of State for Petroleum Resources (Gas), Ekperikpe Ekpo, said the licensing round reflected the Federal Government’s commitment to transparency, competitiveness and credibility.

“The Federal Government remains firmly committed to creating an enabling environment that attracts investment, accelerates exploration and production, and unlocks the full value of Nigeria’s hydrocarbon resources,” Ekpo said.