.. First Bank MD urges more Fintech investment
Artificial intelligence (AI) could widen the global jobs gap, with about 800 million people potentially left without employment opportunities over the next 10 to 15 years, Finance Minister and Coordinating Minister of the Economy, Taiwo Oyedele, has warned.
Oyedele said estimates presented at the ongoing International Monetary Fund (IMF) and World Bank Group Annual Meetings in Bangkok, Thailand, suggested that about 1.2 billion people could enter the global labour market within the period, while only 400 million new jobs might be created.
He warned that the projected gap posed a serious challenge to governments, particularly developing countries such as Nigeria, where a growing population of young people needs employment and economic opportunities.
The minister said the challenge was not only to attract investment and achieve economic growth, but also to ensure that the expansion of economic activity translated into decent jobs and improved living standards.
His warning comes amid growing debate over the impact of AI on employment, productivity and the future of work, as businesses and governments increasingly adopt new technologies.
Oyedele called for greater investment in skills, technology and businesses capable of creating jobs, while urging policymakers to consider how the benefits of AI could be shared more widely.
He said economic performance should not be measured only by the volume of investment attracted, or the rate of growth in gross domestic product, but also by the number of decent jobs created and the improvement in people’s living conditions.
The warning formed part of discussions at the closing press briefing of the IMF and World Bank meetings, where Nigerian officials addressed the country’s economic reform programme, investment prospects and the challenges facing developing economies.
The Central Bank of Nigeria (CBN) Governor, Olayemi Cardoso, also warned that the growing use of AI presented risks to financial stability and cybersecurity.
Cardoso said Nigeria needed a clear strategy to benefit from the productivity gains associated with the technology, while protecting its financial system against emerging threats.
He disclosed that the CBN had engaged AI specialists to brief its board on the opportunities and risks associated with the technology, reflecting the importance of preparing financial institutions and regulators for changes in the banking industry.
The concerns raised by the Nigerian delegation mirror the growing challenge facing financial institutions, which must take advantage of technology to improve services and efficiency while strengthening protection against increasingly sophisticated cyberattacks.
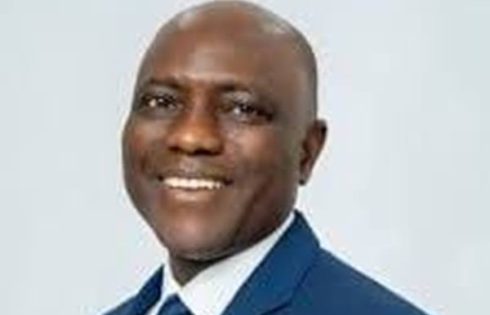
Also, the Chief Executive of First Bank of Nigeria, Olusegun Alebiosu, has said the bank has invested more than N6 billion annually in cybersecurity to protect its systems against cybercriminals. He said the growing use of AI has increased the need for stronger safeguards, even as it creates opportunities to improve banking operations.
The First Bank chief, who spoke in Abuja on the sidelines of the 19th Chartered Institute of Bankers of Nigeria Annual Banking and Finance Conference, said the bank maintained round-the-clock surveillance of its systems, enabling it to detect and take down millions of cyber threats every month.
He said the bank planned to increase its cybersecurity spending, as its business continued to expand and digital operations became more extensive.
“The bank has already established a command centre to monitor its franchise across the globe and counter emerging threats,” he said.
The command centre, according to the bank chief, enables the institution to monitor its operations across different locations and respond to threats targeting its systems.
Alebiosu said the increasing sophistication of cyber threats required banks to remain vigilant and continuously strengthen their defences, adding that AI has heightened cybersecurity risks, making it necessary for financial institutions to invest in the technology and the expertise required to protect customers and their operations.
However, he cautioned against viewing AI only as a source of danger, saying the technology could deliver substantial benefits to banks if the associated risks were properly managed.
On the role of AI in banking, Alebiosu said it could create major opportunities to improve efficiency, speed up processes and support the collection and analysis of data.
He said AI could provide more opportunities than threats for the banking industry if financial institutions put appropriate safeguards in place.
According to him, the technology could help banks carry out tasks more efficiently and gather large amounts of data within a short period, potentially improving the speed of decision-making and the delivery of services.
His comments point to the dual challenge confronting the banking industry: adopting technologies that can reduce operating costs and improve customer service, while preventing criminals from using the same tools to develop more effective cyberattacks.
The growing role of AI therefore places pressure on banks to balance technology investment with cybersecurity spending, staff training and effective risk management, Alebiosu stated.